 By
For generations, personal finance was an exercise in hindsight. Balancing a physical checkbook, collecting paper receipts in an envelope, or manually keying line items into an unwieldy spreadsheet was essentially an autopsy of money already spent. By the time a household realized it had overextended its budget on dining out or utility bills, the billing cycle had already closed, the funds had vanished, and the opportunity for corrective action had passed.
The rapid rise of modern financial applications has fundamentally rewritten that dynamic. Today, smartphones function as continuous, pocket-sized command centers for everyday liquidity, long-term capital allocation, and debt management. By marrying open-banking APIs with behavioral psychology and automated computing, fintech platforms have shifted money management from an agonizing retrospective chore into an active, real-time feedback loop.
The Death of the Monthly Financial Autopsy
The most consequential change financial apps have introduced is instantaneous visibility. In the past, consumers had to log into disparate portals across retail banks, credit unions, credit card issuers, and retirement custodians to piece together their financial standing. This fragmentation created substantial cognitive friction, leading many people to practice financial avoidance until an overdraft alert or tax deadline forced their hand.
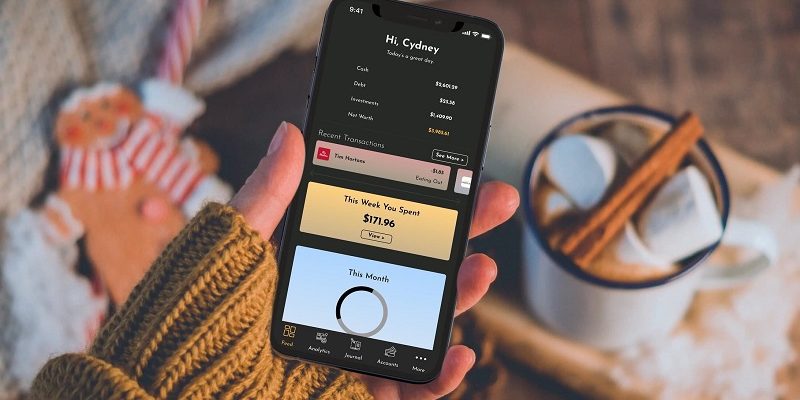
Contemporary budgeting platforms dismantle this friction through account aggregation. By pulling live transactional feeds into a unified dashboard, these platforms give users an immediate picture of their true net worth and available cash flow.
More importantly, real-time transaction categorization turns passive numbers into actionable intelligence. When an app pings your phone thirty seconds after an impulse purchase, noting that you have consumed eighty percent of your discretionary budget halfway through the month, the psychological calculus shifts immediately. The feedback is prompt, relevant, and directly tied to an ongoing behavior, allowing consumers to self-correct during the billing period rather than lamenting overages weeks later.
Eliminating the Willpower Barrier Through Automated Saving
Traditional financial advice has always preached the virtue of paying yourself first. Yet for millions of Americans, manually transferring money from a checking account into a savings vehicle requires an ongoing exercise in willpower, competing against immediate lifestyle desires and unexpected expenses.
Financial technology has essentially removed willpower from the wealth-accumulation equation through automated rules and micro-transactions.
Passive Consistency vs. Active Discipline
Instead of demanding a conscious decision each month, automated apps operate quietly in the background:
-
Algorithmic micro-saving: Platforms analyze checking account volatility, spending patterns, and upcoming bill cycles to identify safe margins of cash. The software then siphons small amounts into dedicated savings vaults without triggering an overdraft or disrupting daily expenses.
-
Round-up mechanisms: Rounding everyday debit or credit transactions up to the nearest dollar and sweeping the spare change into high-yield savings accounts or diversified investment portfolios turns routine consumption into automated accumulation.
-
Rules-based allocations: Users can program customized conditional commands, such as diverting a percentage of every direct deposit directly into an emergency fund or a vacation reserve the millisecond payroll clears.
By automating these micro-decisions, apps leverage the behavioral concept of status quo bias in favor of the consumer. Saving transitions from an arduous recurring discipline into an ambient background process that functions regardless of mood, fatigue, or temptation.
Democratizing Wealth Building and Retail Investing
Until relatively recently, retail investing carried intimidating structural barriers. Traditional brokerages required steep opening deposits, charged hefty commissions per trade, and reserved their most sophisticated portfolio tools for high-net-worth clients who could afford private wealth managers.
Investment applications have torn down these gatekept entry points. Zero-commission trading models, fractional share purchases, and automated robo-advisory engines have made institutional-grade portfolio construction accessible to anyone with a spare five dollars.
Fractional investing has fundamentally changed how beginners engage with the market. A worker who cannot afford a single thousand-dollar share of an enterprise technology stock can now invest twenty dollars directly into that company, capturing proportional gains and dividend distributions.
Simultaneously, robo-advisors have automated complex asset-allocation strategies. By assessing a user’s risk tolerance, time horizon, and cash-flow needs, algorithms construct low-cost, globally diversified portfolios using exchange-traded funds. Features that once required a certified financial planner—such as systematic tax-loss harvesting, automated portfolio rebalancing, and dividend reinvestment—run continuously behind the scenes for a fraction of traditional advisory fees.
Unmasking the Subscription Economy and Recurring Leaks
The modern digital economy runs on recurring revenue. From streaming platforms and fitness memberships to software suites and delivery passes, consumers are surrounded by minor monthly charges that fly under the radar. Individually, an eight-dollar charge appears negligible; collectively, recurring subscriptions represent a massive drain on monthly liquidity.
Financial applications provide essential counter-measures against subscription creep. Specialized financial dashboards catalog recurring payments, identify forgotten services, and track creeping price hikes.
Many apps go a step further, offering integrated tools that cancel unused accounts with a single prompt or communicate directly with telecom and utility providers to negotiate lower monthly bills. Restoring visibility to recurring expenses plugs structural cash leaks, instantly freeing up capital that can be redirected toward debt reduction or productive investment.
The Frictionless Trap: Digital Detachment and Security
While the advantages of fintech apps are profound, the complete elimination of financial friction carries distinct psychological and technical risks that consumers must actively manage.
When currency is reduced to digital taps and frictionless biometric approvals, money loses its tactile reality. Psychologists have long observed that people spend more freely when paying with plastic or digital wallets than with physical cash. When budgeting apps make spending, borrowing, and moving money utterly frictionless, it becomes dangerously easy to disconnect daily digital taps from the real labor required to earn those dollars.
Furthermore, gamified trading apps present real hazards for retail investors. By incorporating push notifications, colorful visual rewards, and community leaderboards, some speculative trading platforms encourage frequent, impulsive transactions over patient, long-term indexing. In finance, frequent trading and speculative chasing are reliably correlated with inferior long-term returns.
Finally, relying on interconnected financial software requires robust personal cybersecurity hygiene. Linking checking accounts, retirement funds, and lines of credit to third-party software creates an expanded digital footprint. Consumers must treat these platforms with appropriate rigor: enforcing non-negotiable multi-factor authentication, utilizing unique passwords managed by encrypted vaults, and verifying that their chosen platforms rely on read-only, bank-grade encryption protocols rather than storing raw banking credentials.
Cultivating Sustainable Financial Sovereignty
The ultimate value of financial apps lies not in their ability to hoard charts, generate colorful spending graphs, or flash market updates every ten minutes. Their true power rests in how effectively they reduce the administrative friction of staying solvent.
When calibrated with care, modern financial tools automate the mundane mechanics of money management—sweeping cash into reserves, balancing portfolios, paying bills on time, and flagging wasteful expenditures. By offloading these repetitive calculations to intelligent software, consumers reclaim valuable mental bandwidth, transforming personal finance from a chronic source of household anxiety into an automated system that serves their long-term life goals.



Comments